Cost overruns are extraordinarily common in every single sector of performance, every industry, and every part of the world. They can reach enormous magnitudes in both short-term and long-term projects, seriously damaging their financial health and reducing chances for success.
Nevertheless, a comprehensive and systematic approach to cost management is a definite remedy to this problem. It serves to align project needs with available resources, supervise current and future expenses, and analyze cost performance. Thus, it can assist you in avoiding the risk of cost overrun a great deal.
In this article, we will define what project cost management is, discuss its role in project planning, and overview its major components to help you see why you must invest in cost management yourself.
What Is Project Cost Management?
“Cost Management is a function which includes the processes that are required to maintain effective financial control of projects (evaluating, estimating, budgeting, monitoring, analyzing, forecasting and reporting the cost information).”: PMI
It aims to:
- Calculate how much money is needed to perform tasks and duties involved in the project.
- Develop a project budget and allocate funds as per the results of cost estimation.
- Track down how much is spent on project-related activities and encourage compliance with the created budget.
- Gather statistical data regarding actual project expenses to inform future decision-making.
When all these objectives are achieved, you will take project costs under control, reduce the risk of loss, and maximize profit.
Role of Cost Management in Project Management
Cost management is an integral part of project management in general, and its contribution to the project’s success is more than vital. To understand why, let’s identify the primary purpose of project management and explore the issue of project constraints in some detail.
Project Planning and the Triple Constraint
As such, the primary strive of project management is to attain formulated project goals within a specific timeframe, scope, and budget. These three restrictive parameters are illustrated within the Triple Constraint Model as interdependent: a change in one of them inevitably entails changes in two others.
For instance, when the project’s scope is enlarged, the number of efforts and resources needed to complete it increases. As a result, the deadline and the cost of that project become altered as well.
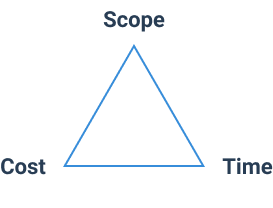
In the present-day world of business, it is particularly important to remember the interdependence among project scope, timeframes, and costs. The modern environment is rapidly evolving and extremely competitive. It makes managers compromise at every step and choose between affordability and quality, speed and effectiveness, stakeholder satisfaction, and profitability. The list goes on.
Thus, you must always be aware of the fact that a decision to complete the project in a shorter term will entail the necessity to reduce the volume of project-related tasks or invest more money in skilled personnel and technology. Otherwise, you will likely fail to meet the deadline or the quality of your work will badly suffer.
Overall, the Triple Constraint Model is here to remind you of that.
Why Cost Planning Is Especially Important?
Statistical data shows that cost is the most critical factor in defining project failures and success:
- According to the McKinsey-Oxford study on performance in the IT sector, cost overruns in software projects can reach 66% on average, and in projects that are not related to software: 43%.
- However, IT companies are not the only ones to bear financial risks after going over their project budgets. A recent review of evidence from international construction industries revealed that an average cost overrun in medium-sized projects is as high as 32.5%, whereas in megaprojects, the number may reach 88%.
These statistics indicate that regardless of all the advancements in the practice and theory of project cost management throughout the last decades, many projects still suffer the consequences of inadequate expenditure prediction and control.
Partially, project cost overruns may be attributed to the lack of a clear strategic plan and managers’ inability to consider potential risks and environmental changes. However, cost underestimation can be validly named the leading reason why businesses go far above their budgeted expectations.
So, unlike a thoughtless attitude to cost management, a serious and careful approach to this essential practice can take you and your project a long way.
The four cost management processes, by their standard names
Project cost management is usually broken into four processes: plan cost management, estimate costs, determine budget, and control costs. Those are the names used in the PMI framework, and knowing them matters because every other guide, exam question and tool uses them too.
| Process | What it produces | Where it goes wrong |
|---|---|---|
| Plan cost management | The cost management plan: units, precision, thresholds, who approves what | Skipped entirely, so nobody agrees what counts as an overrun |
| Estimate costs | A cost for each work package, with a stated confidence | Estimated from memory rather than from recorded actuals |
| Determine budget | The cost baseline, which is what performance is measured against | No baseline is saved, so later variance cannot be calculated |
| Control costs | Variance against the baseline, and the decisions that follow | Reported monthly, which is too late to change anything |
The third row is the one to check on your own projects. A budget that was never saved as a baseline is a number somebody remembers, and cost control against a remembered number is not control.
Each process in practice
Day to day, those four processes look like four pieces of work. Scoping comes first because you cannot cost work you have not defined, and the formal plan cost management step is usually folded into it on smaller projects.
- Work scope planning, which feeds plan cost management
- Cost estimation, which is estimate costs
- Budgeting, which is determine budget
- Spending control, which is control costs
Each one is covered below, with what it produces and what it is worth getting right.
Work Scope Planning
To comprehend how much money is required to deliver a project, you must know it from the inside out: its short-term objectives, long-term goals, and the environment where it is going to be realized. In other words, you need an evidence-based and thorough plan.
Here’s why:
“Many projects fail either because they bite off more than they can chew and thus grossly underestimate time and money or because a significant part of the work has been overlooked. One tool that can help you avoid these problems is the Work Breakdown Structure (WBS), which aids in the process of determining scope and tasks and developing estimates.”: HBR
A WBS is essentially a hierarchical diagram of all the things you should accomplish within a project. It starts with major milestones or project phases at the top of the diagram and ends with smaller work packages, e.g., the groups of tasks that must be done to attain the desired deliverables.
For example, a WBS for a content marketing project could look something like this:

In this WBS diagram, major project activities are highlighted in blue, mid-level deliverables are highlighted in red, and orange blocks designate work packages.
As a result of representing your entire work scope in such a visual format, you get a clear picture of the activities involved in the project. Then, you can use the WBS to evaluate which resources you need, how many of them you already have, and how much you still must acquire. After that, you may proceed toward a more detailed estimation of project-related expenses.
Get a free WBS template here. 👈
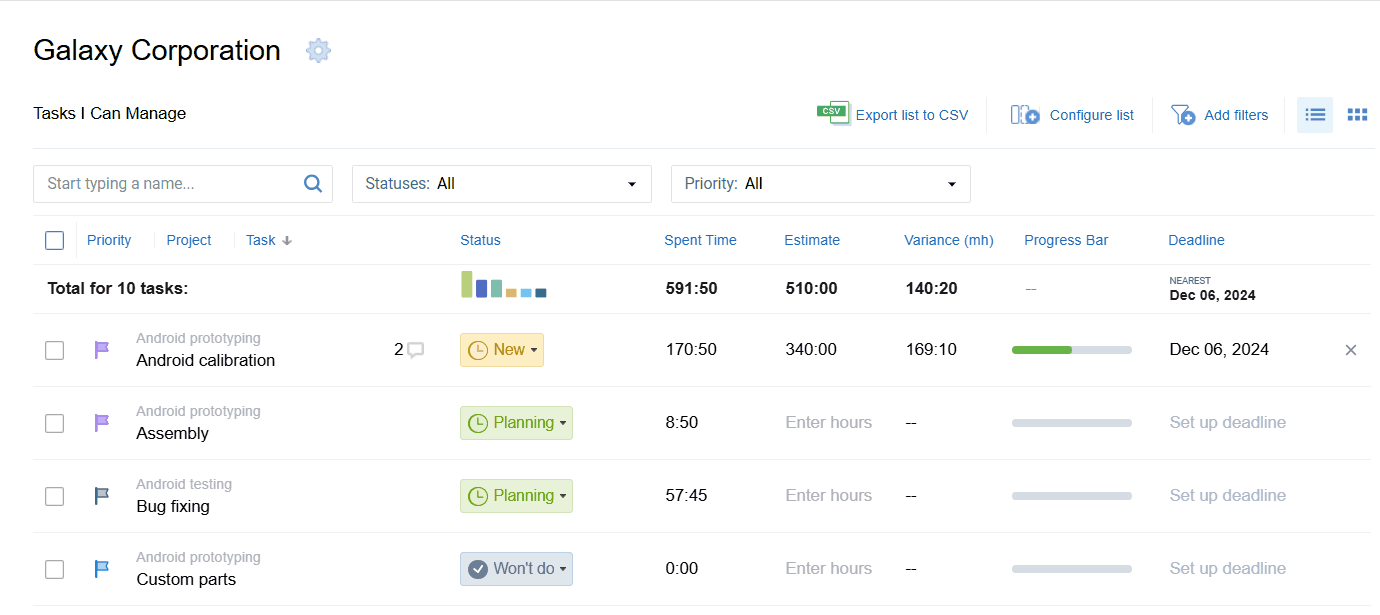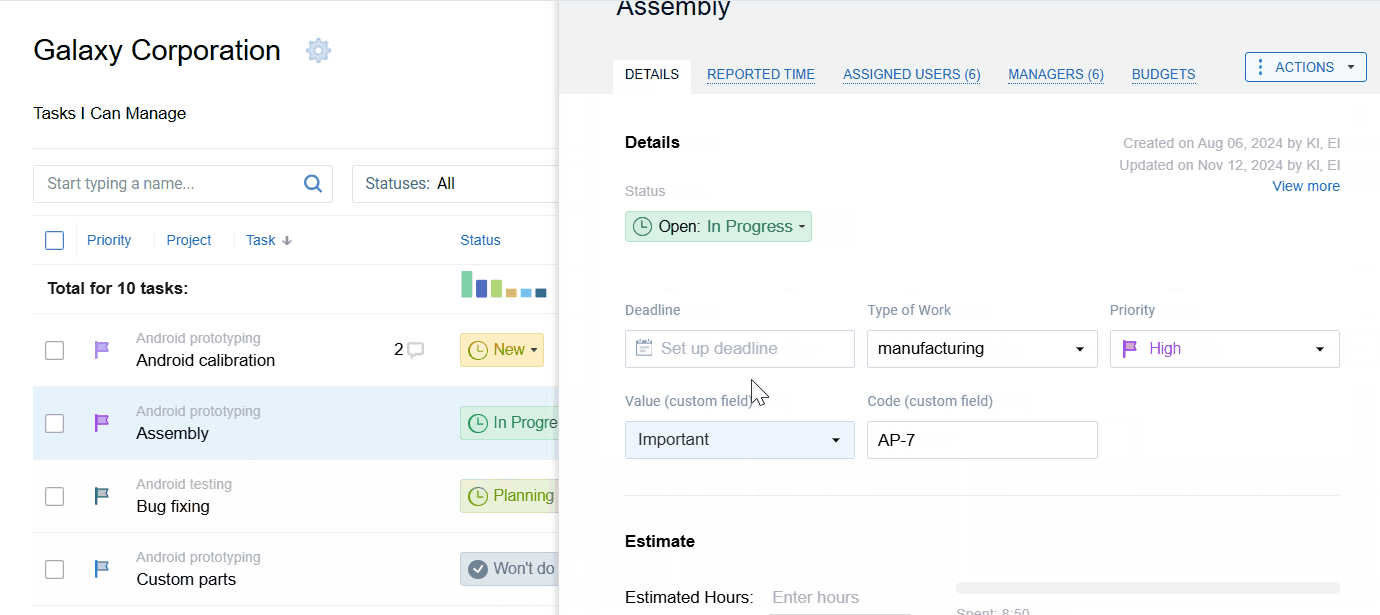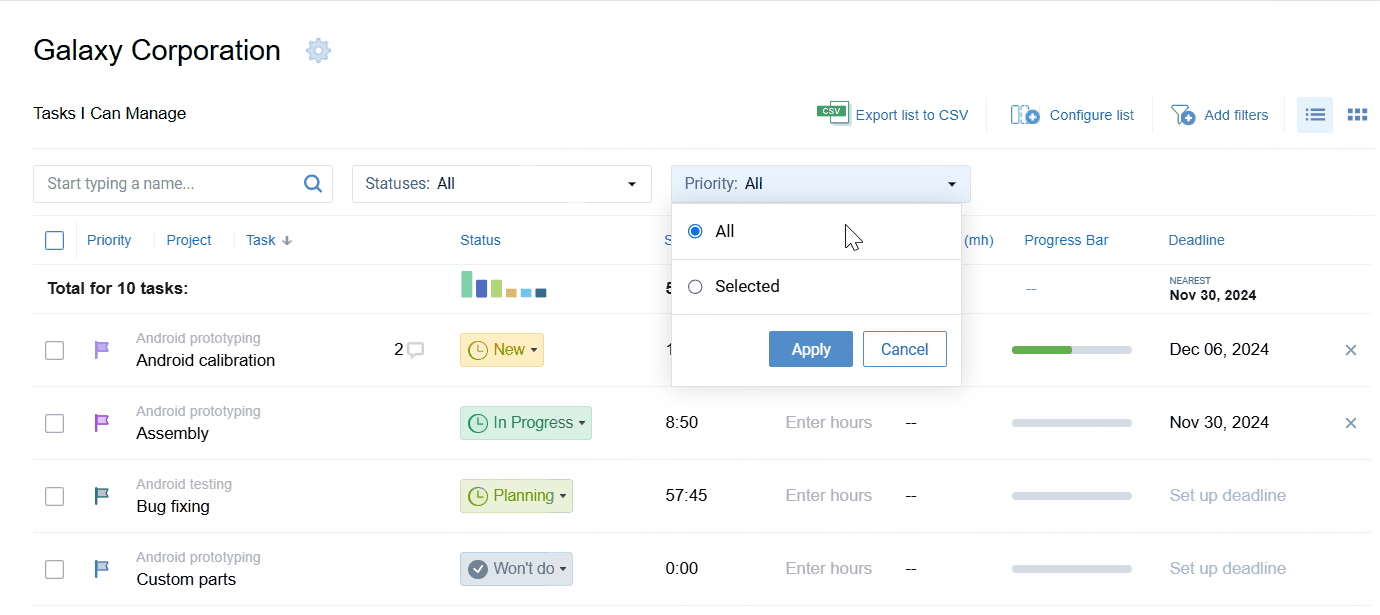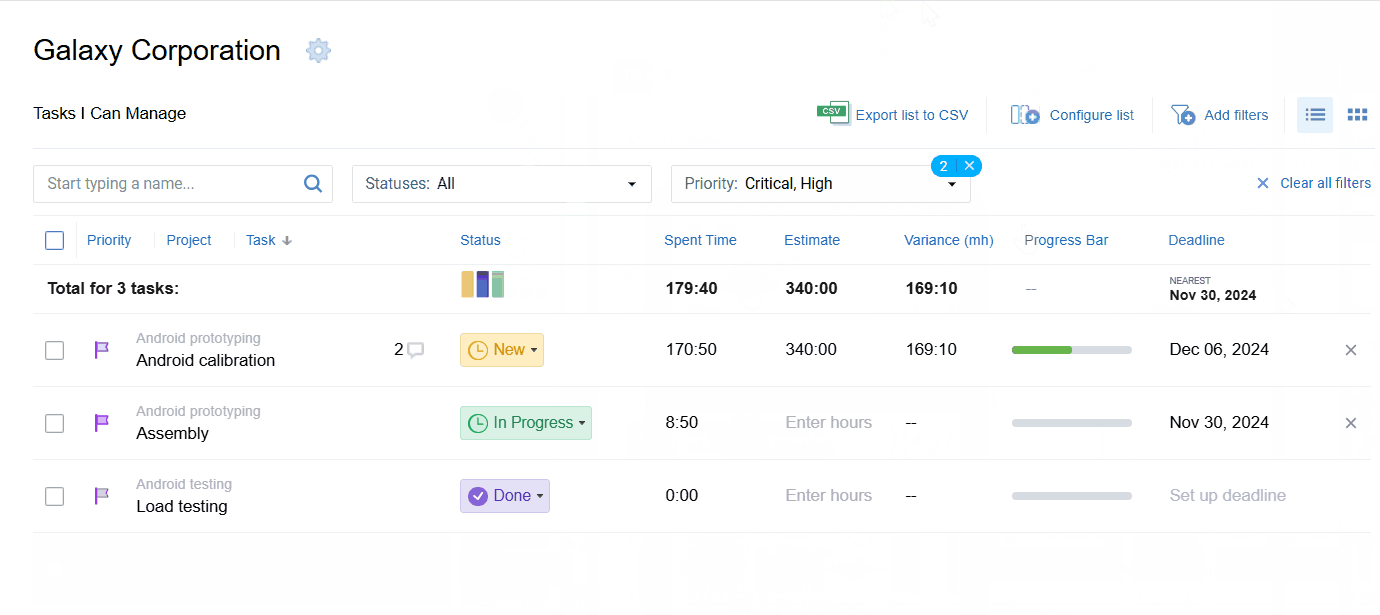
Use actiTIME to plan out your project scope the easy way: create as many tasks as you want, set deadlines and priorities, allocate work to employees, and then track their performance via a variety of visual progress tools.
Cost Estimation
” Cost Estimating is the process of assembling and predicting the costs of a project. It encompasses the economic evaluation, project investments cost and predicting or forecasting of future trends and costs.”: PMI
Let’s break down the three elements of cost estimation one by one:
Economic evaluation is meant to give you an idea of whether your project is financially and technically feasible. It’s carried out at the initial planning stage so where you produce rough estimates of project expenses and potential profits.
Project investment cost implies more accurate cost estimation. That’s the phase where you define your budget and develop a more precise picture of the majority of expenses your project will incur (at least at the start of its life cycle).
You can use your WBS (and resource breakdown structure) to sort out project costs: since you already know what you need to do and what type of resources are required, the primary task here is to identify their prices as accurately as possible. Then, just sum up the numbers to see how much the project will cost you as a whole.
Cost forecasting is about looking into potential trends, opportunities, and risks. You need to perform a risk-based cost analysis. Evaluate potential loss due to a delay in the supply of essential production materials, some technical issues, or even the dismissal of a very important employee. Choose anything that makes sense in your situation and add the predicted cost of the event to other estimation results.
Whereas regular cost estimation allows you to see if the planned project activities are financially feasible and optimize them accordingly, risk-based cost assessment shows how much money you need to use as a cushion against unpredictable and costly events.
Get free risk assessment templates here. 👈
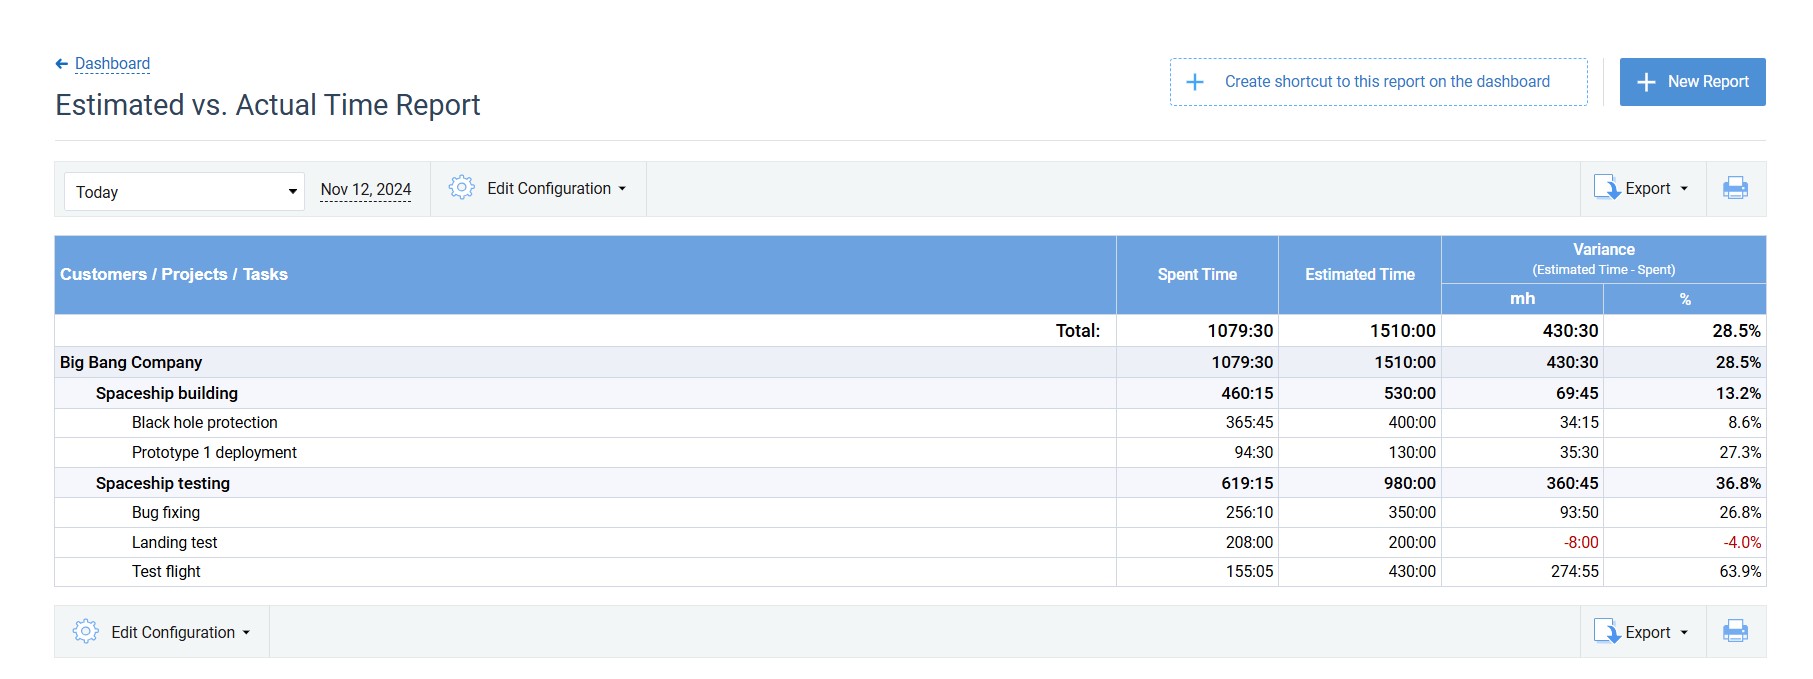
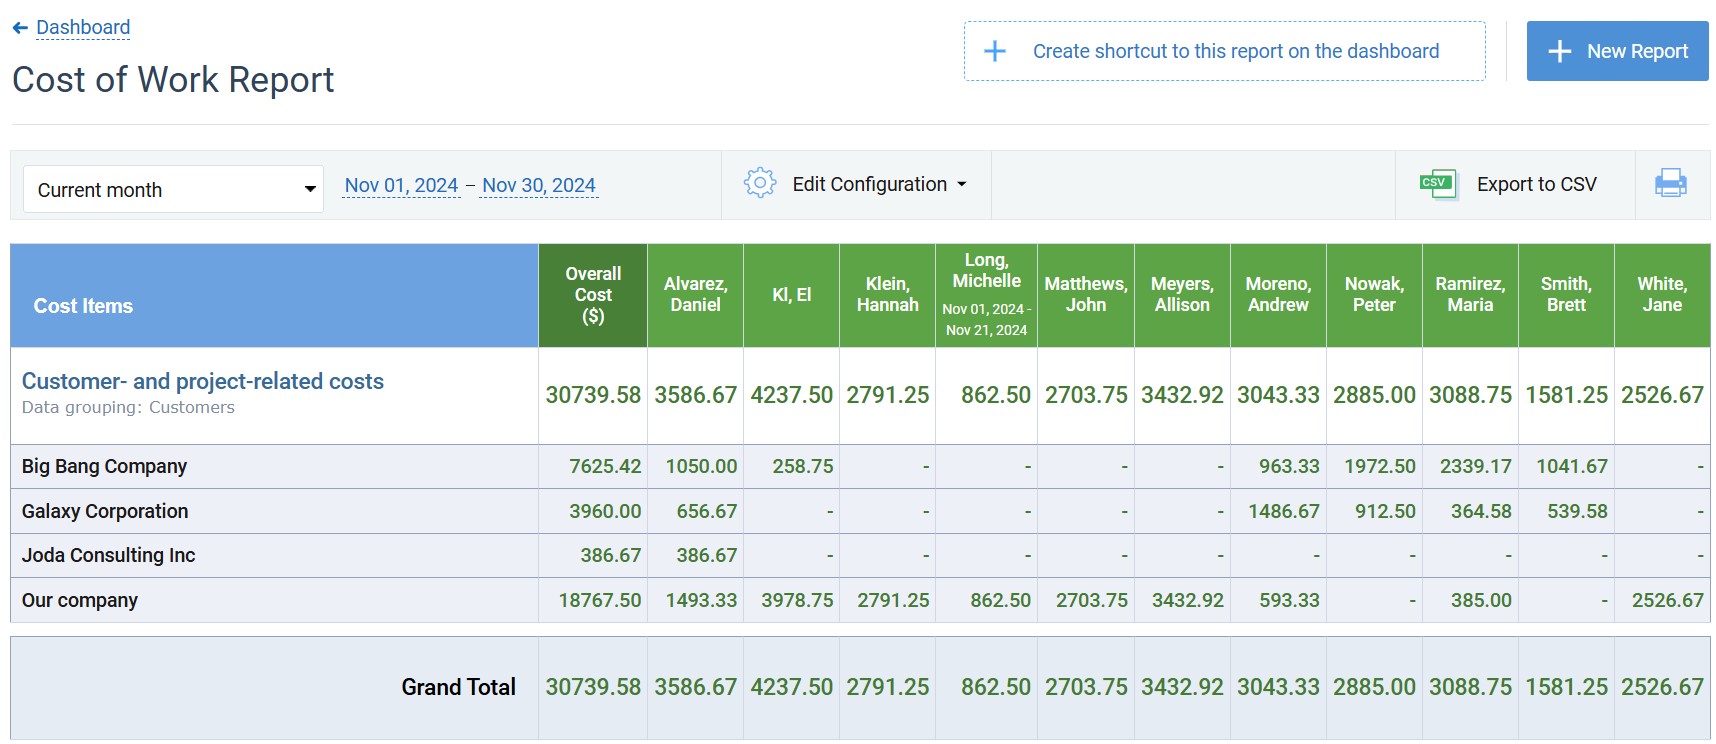
actiTIME reports provide a wealth of invaluable data to inform your project estimation process: from detailed hour tracking results to staff-related expenses and billable time per task. Apply this historical information in analogous cost estimation to enhance resource management in your future work.
Budgeting
A budget is a summary of all expenditures and/or revenues involved in the project. It states the final cost estimates, clarifies how much money you will have at different stages in the project’s life cycle, and indicates how much funds could and should be allocated to certain project activities.
In the end, a well-developed project budget serves as the foundation for cost control that your team must perform to avoid excess spending and get more profit.
There are several ways to approach your project budgeting process:
Incremental project budgeting means you use time estimates or historical time tracking data from previous projects to estimate your project costs and set budgets.
Activity-based budgeting starts by identifying your ideal revenues. Taking from there, you estimate how much work must be done to achieve the desired financial goal, estimate how much money you should put into that work, and create your budget using those estimates.
Value-based budgeting requires you to prioritize budget items based on their value for your project or business as a whole. In other words, you need to identify the resources and activities that are absolutely essential to your project and financial goals and eliminate the insignificant ones from your budget: only the important stuff remains.
Zero-based budgeting requires you to allocate budget based on the criteria of necessity and efficiency. “Management starts from scratch and develops a budget that only includes operations and expenses essential to running the business; there are no expenses that are automatically added to the budget” (CFI).
Speed up your budgeting process with our free project budget templates. 👇
Cost Control
Cost control is all about identifying, monitoring, and evaluating project costs in order to reduce expenses and maximize the revenues of a business. It is carried out by comparing the actual financial performance of the project with expectations stated in the budget.
In an ideal situation, your team should always comply with budget estimates. However, since cost overruns are frequent and are difficult to control 100% of the time, it is important to ensure that all expenses are properly recorded and, consequently, subjected to a thorough analysis.
By comparing data on actual project costs with those stated in the budget, managers can detect flaws in their approach to project cost management and disclose factors that were left without appropriate attention but require consideration. In this way, it becomes possible to enhance the accuracy and quality of cost management and improve the financial performance of future projects.
Here is a list of major procedures involved in cost control:
Cost tracking, i.e., the systematic monitoring of ongoing project expenses. This essential project cost management activity helps to collect important performance data and identify the risk of cost overruns early on. To attain better results, it’s vital to do it every single day of your work on a project. Luckily, you don’t have to track project costs manually: there are myriads of automated cost tracking software tools on the web. Check out actiTIME as an example.
Next, we have budget variance analysis, i.e., the comparison of your actual cost of work performed (ACWP) to the budgeted cost of work performed (BCWP), which is the budgeted value of what has actually been finished rather than what was scheduled. To perform this analysis, use the following simple formula:
Although cost control is never painless, by approaching it systematically and attentively, you will increase the chance of the project’s success to a substantial degree.
BCWP and ACWP are the older names for the same two quantities that earned value analysis calls earned value and actual cost, so the formula above is cost variance under a different label. The section below works through what those figures tell you and what to do about the answer.
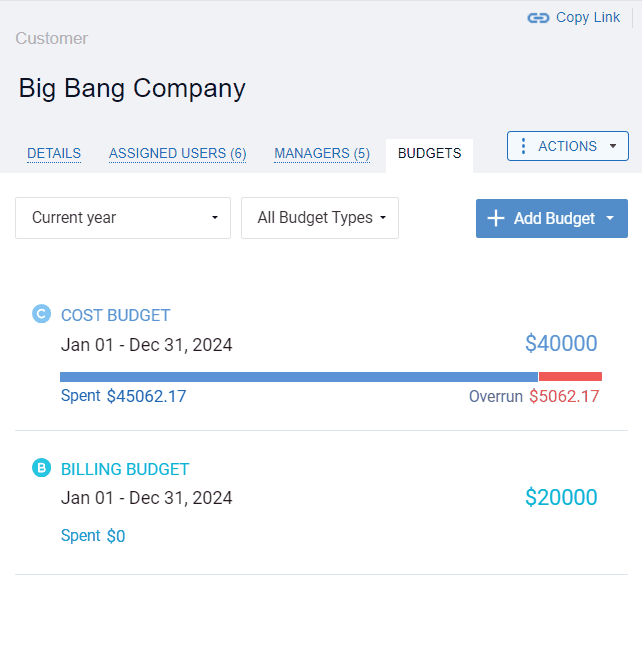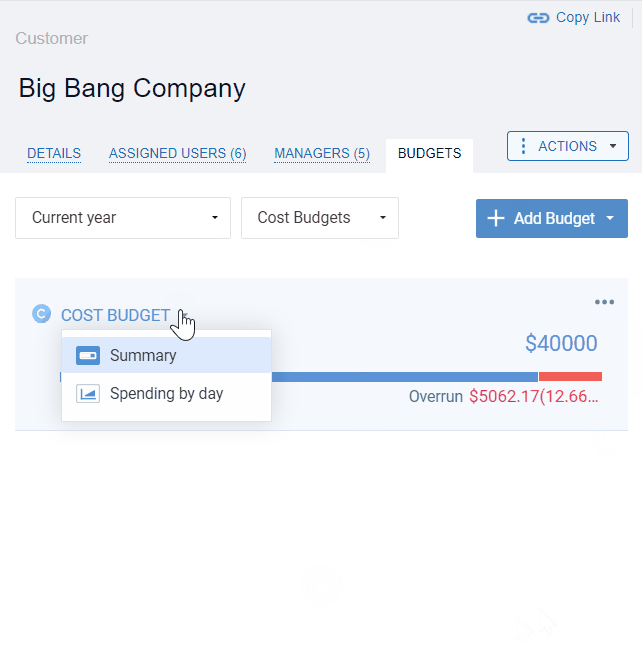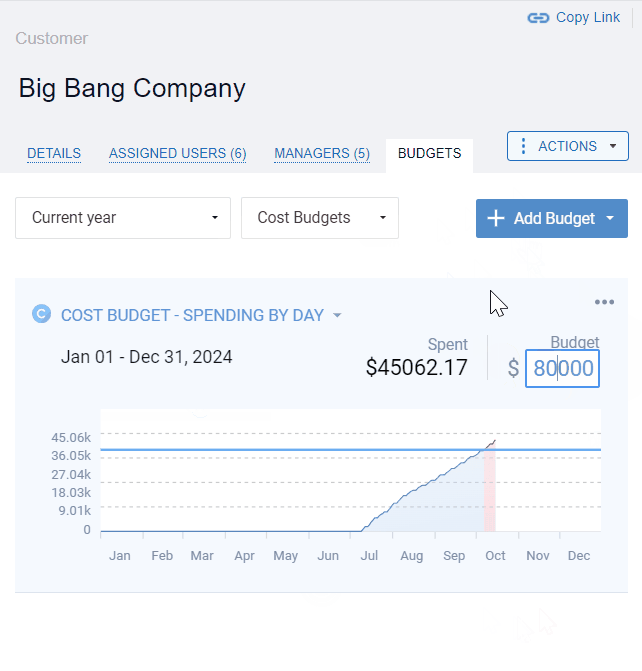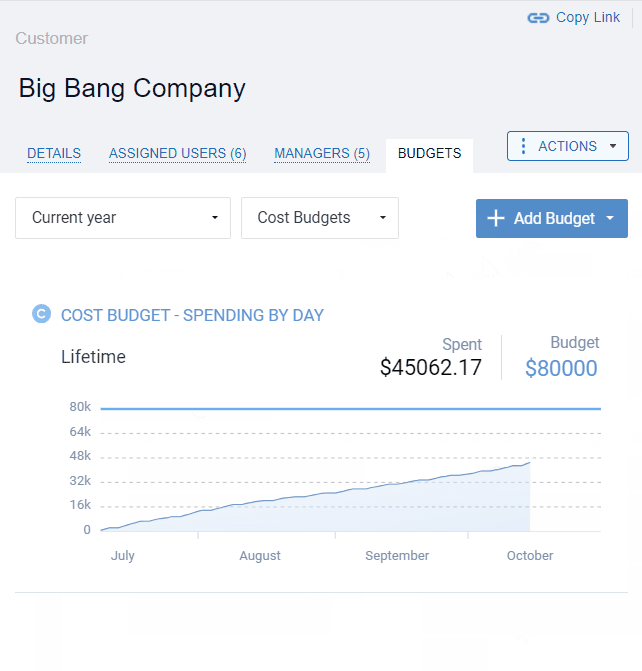
actiTIME’s visual budget tracker is the ultimate tool for cost control! It highlights budget overruns in red and lets you analyze the collected progress data as an overall summary of the entire budgeting period or a detailed breakdown by day.
How project cost control actually works
Comparing money spent against money budgeted tells you nothing on its own, because it ignores how much work has been delivered for that money. Earned value fixes that by putting three numbers side by side.
- Planned value. What the baseline says should have been spent by today.
- Earned value. The budgeted value of the work actually finished.
- Actual cost. What has really been spent.
Project cost control turns on two figures. Cost variance is earned value minus actual cost. The cost performance index is earned value divided by actual cost, and anything below 1.0 means you are getting less than a dollar of value per dollar spent. That index is the whole point of cost control in project management: it tells you the size of the gap while there is still budget left to close it, which a simple spent-versus-budgeted comparison never does. Our guide to cost tracking tools works through the full calculation with numbers.
The 50/50 rule
The 50/50 rule is a way of crediting progress without arguing about percentages: a task earns 50% of its budgeted value when it starts, and the remaining 50% when it finishes.
The point is objectivity. Nobody has to estimate whether something is 60% or 70% done, and the person doing the work cannot influence the figure. It suits projects with many short work packages and frequent reporting, where asking for a percentage on each one would cost more than the information is worth.
The stricter variant is the 0/100 rule, where nothing is credited until the task is complete. That understates progress but removes the risk of a half-finished task looking half-paid-for, which matters when work packages run long.
Frequently asked questions
What is project cost management?
Project cost management is the process of planning, estimating, budgeting and controlling what a project costs, so it can be completed within an approved budget. It runs from before the work starts, when the rules and estimates are set, through to closure, when the actuals become the reference data for the next project.
What are the four types of costs in project management?
Costs are classified two ways at once, giving four labels. By whether they change with volume: fixed costs stay the same regardless of how much work is done, variable costs rise and fall with it. By whether they can be traced to one project: direct costs belong to a single project, indirect costs are shared and allocated across several. A contractor’s hours are both variable and direct; office rent is both fixed and indirect. Our guide to the project cost breakdown covers the full classification including sunk and opportunity costs.
What is the 50/50 rule in project management?
It is an earned value convention: a task is credited with 50% of its budgeted value as soon as it starts, and the other 50% when it is finished. Only the start and finish dates need reporting, which removes the guesswork from percentage-complete estimates and stops the person doing the work influencing the number. The 0/100 rule is the stricter version, crediting nothing until completion.
What goes into a cost management plan?
A cost management plan sets the rules everything else follows: the units and level of precision used for estimates, the control thresholds that trigger action, who approves a change to the budget, and how performance will be measured and reported. The cost management plan is produced before any estimating happens, and its absence is why teams later disagree about whether a project is over budget at all.
What is the difference between cost estimating and budgeting?
Estimating produces a cost for each piece of work. Budgeting aggregates those estimates into an authorised total spread across time, and saves it as the cost baseline. The distinction matters because only the baseline can be measured against; a pile of estimates with no baseline gives you no way to calculate variance later.
Streamline Project Cost Management with actiTIME
To improve your project cost management outcomes and track project budgets with ease, consider adopting actiTIME. This multifunctional software solution has all you need to track performance costs, manage project budgets, and analyze data in depth.
Start by planning out your entire project scope: set deadlines and priorities for tasks, share other important details via comments, and allocate work to employees. Then, use detailed historical data from time and money reports to get more accurate cost and time estimates and analyze your financial performance at the end of the project.
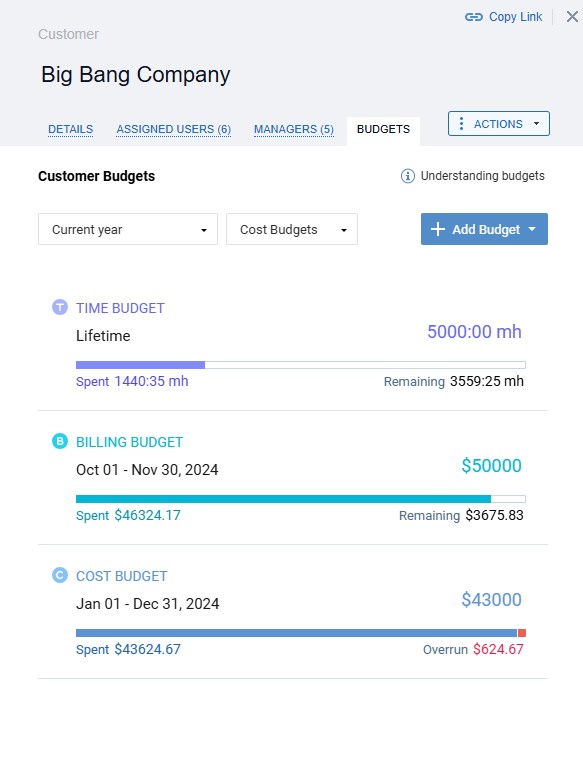
You can also set different types of budgets for entire projects and customers or individual tasks in actiTIME! Each budget comes with a visual progress bar that makes it super easy to monitor the use of resources over time and promptly address the risk of project overruns.
On top of that, actiTIME offers a variety of progress tracking tools to monitor project costs and other resources: visual estimate and budget trackers, multiple charts and reports, real-time widgets, Kanban board, and more!
Explore all these handy actiTIME features firsthand during a free 30-day trial.